-
6142 Miramar Parkway Suite D, Miramar, FL 33023
Sep 16, 2026
Miramar & South Florida Small Business Health Insurance Guide 2026: Group Plans, Level-Funded vs Fully Insured & ICHRAs
Learn the key differences between level-funded and fully insured plans. Make informed health care choices that suit your needs and budget effectively.
By Erick Sanon, BrightBridge Insurance
Navigating the landscape of small business health insurance Miramar FL and greater South Florida can be complex. Business owners often find themselves overwhelmed by the multitude of options available, from traditional fully insured plans to increasingly popular level-funded and individual coverage HRAs (ICHRAs). This comprehensive guide aims to equip small business owners—whether entrepreneurs or established businesses—with crucial insights into the current health insurance offerings, funding models, eligibility criteria, and strategies to optimize their benefits packages. By clearly understanding these nuances, businesses can make informed choices that benefit both their employees and their bottom line. Sections to explore include overviews of group health insurance plans South Florida, employer requirements in Florida, a comparison of funding models, and a detailed look at ancillary group benefits.
Group Health Insurance Plans Overview
Group health insurance plans South Florida provide an essential safety net for small business employees, covering a wide range of medical expenses through collective risk-sharing among the insured. Understanding these types of plans is crucial for business owners as they seek to attract and retain talent while ensuring compliance with regulations. Group plans generally fall into two main types: fully insured plans, where the employer pays a fixed premium to an insurer for health coverage, and self-funded or level-funded plans, which allow businesses to pay for claims as they arise, providing potential cost savings. Group benefits
The importance of group health insurance cannot be overstated, as it enhances employee satisfaction and productivity while safeguarding the business from potential liabilities related to health-related absences. For more tailored solutions, companies like BrightBridge Insurance specialize in navigating these options to create customized plans that meet the specific needs of small businesses in South Florida.
The 2026 Small Business Health Insurance Landscape in Miramar and South Florida
The health insurance landscape for small business health insurance Miramar FL and broader South Florida has evolved significantly in recent years, influenced by regulatory changes and emerging trends. Recent updates to local and federal legislation affect how small businesses approach employee health benefits, emphasizing the importance of compliance with the Affordable Care Act (ACA) and state-level mandates. Additionally, market trends indicate a shift towards more personalized insurance solutions, including level funded health insurance Broward County plans and ICHRAs, which offer employers more flexibility in managing their health expenses.
Local market conditions also play a critical role, with various providers enhancing their offerings to meet the demands of small businesses. Understanding these trends is crucial for any business owner aiming to stay competitive while providing quality health coverage.
Employer Requirements: Florida Small Group Rules & Qualifying Criteria
Navigating the Florida small group health insurance requirements can be daunting for employers. Key criteria stipulate that small businesses must have between 2 to 50 eligible employees to qualify for small group health plans. Additionally, employers need to provide a minimum contribution towards premiums, typically at least 50% for employee coverage and 30% for dependents. Compliance with the ACA mandates, including essential health benefits coverage, is necessary to avoid penalties and ensure employees secure the necessary healthcare access.
Moreover, employers are required to adhere to proper enrollment procedures and maintain accurate records to substantiate eligibility for health insurance coverage. By understanding these regulations, small business owners can streamline their approach to health benefits and mitigate compliance risks.
Funding Models Compared: Fully Insured vs. Level-Funded vs. Self-Funded Group Plans
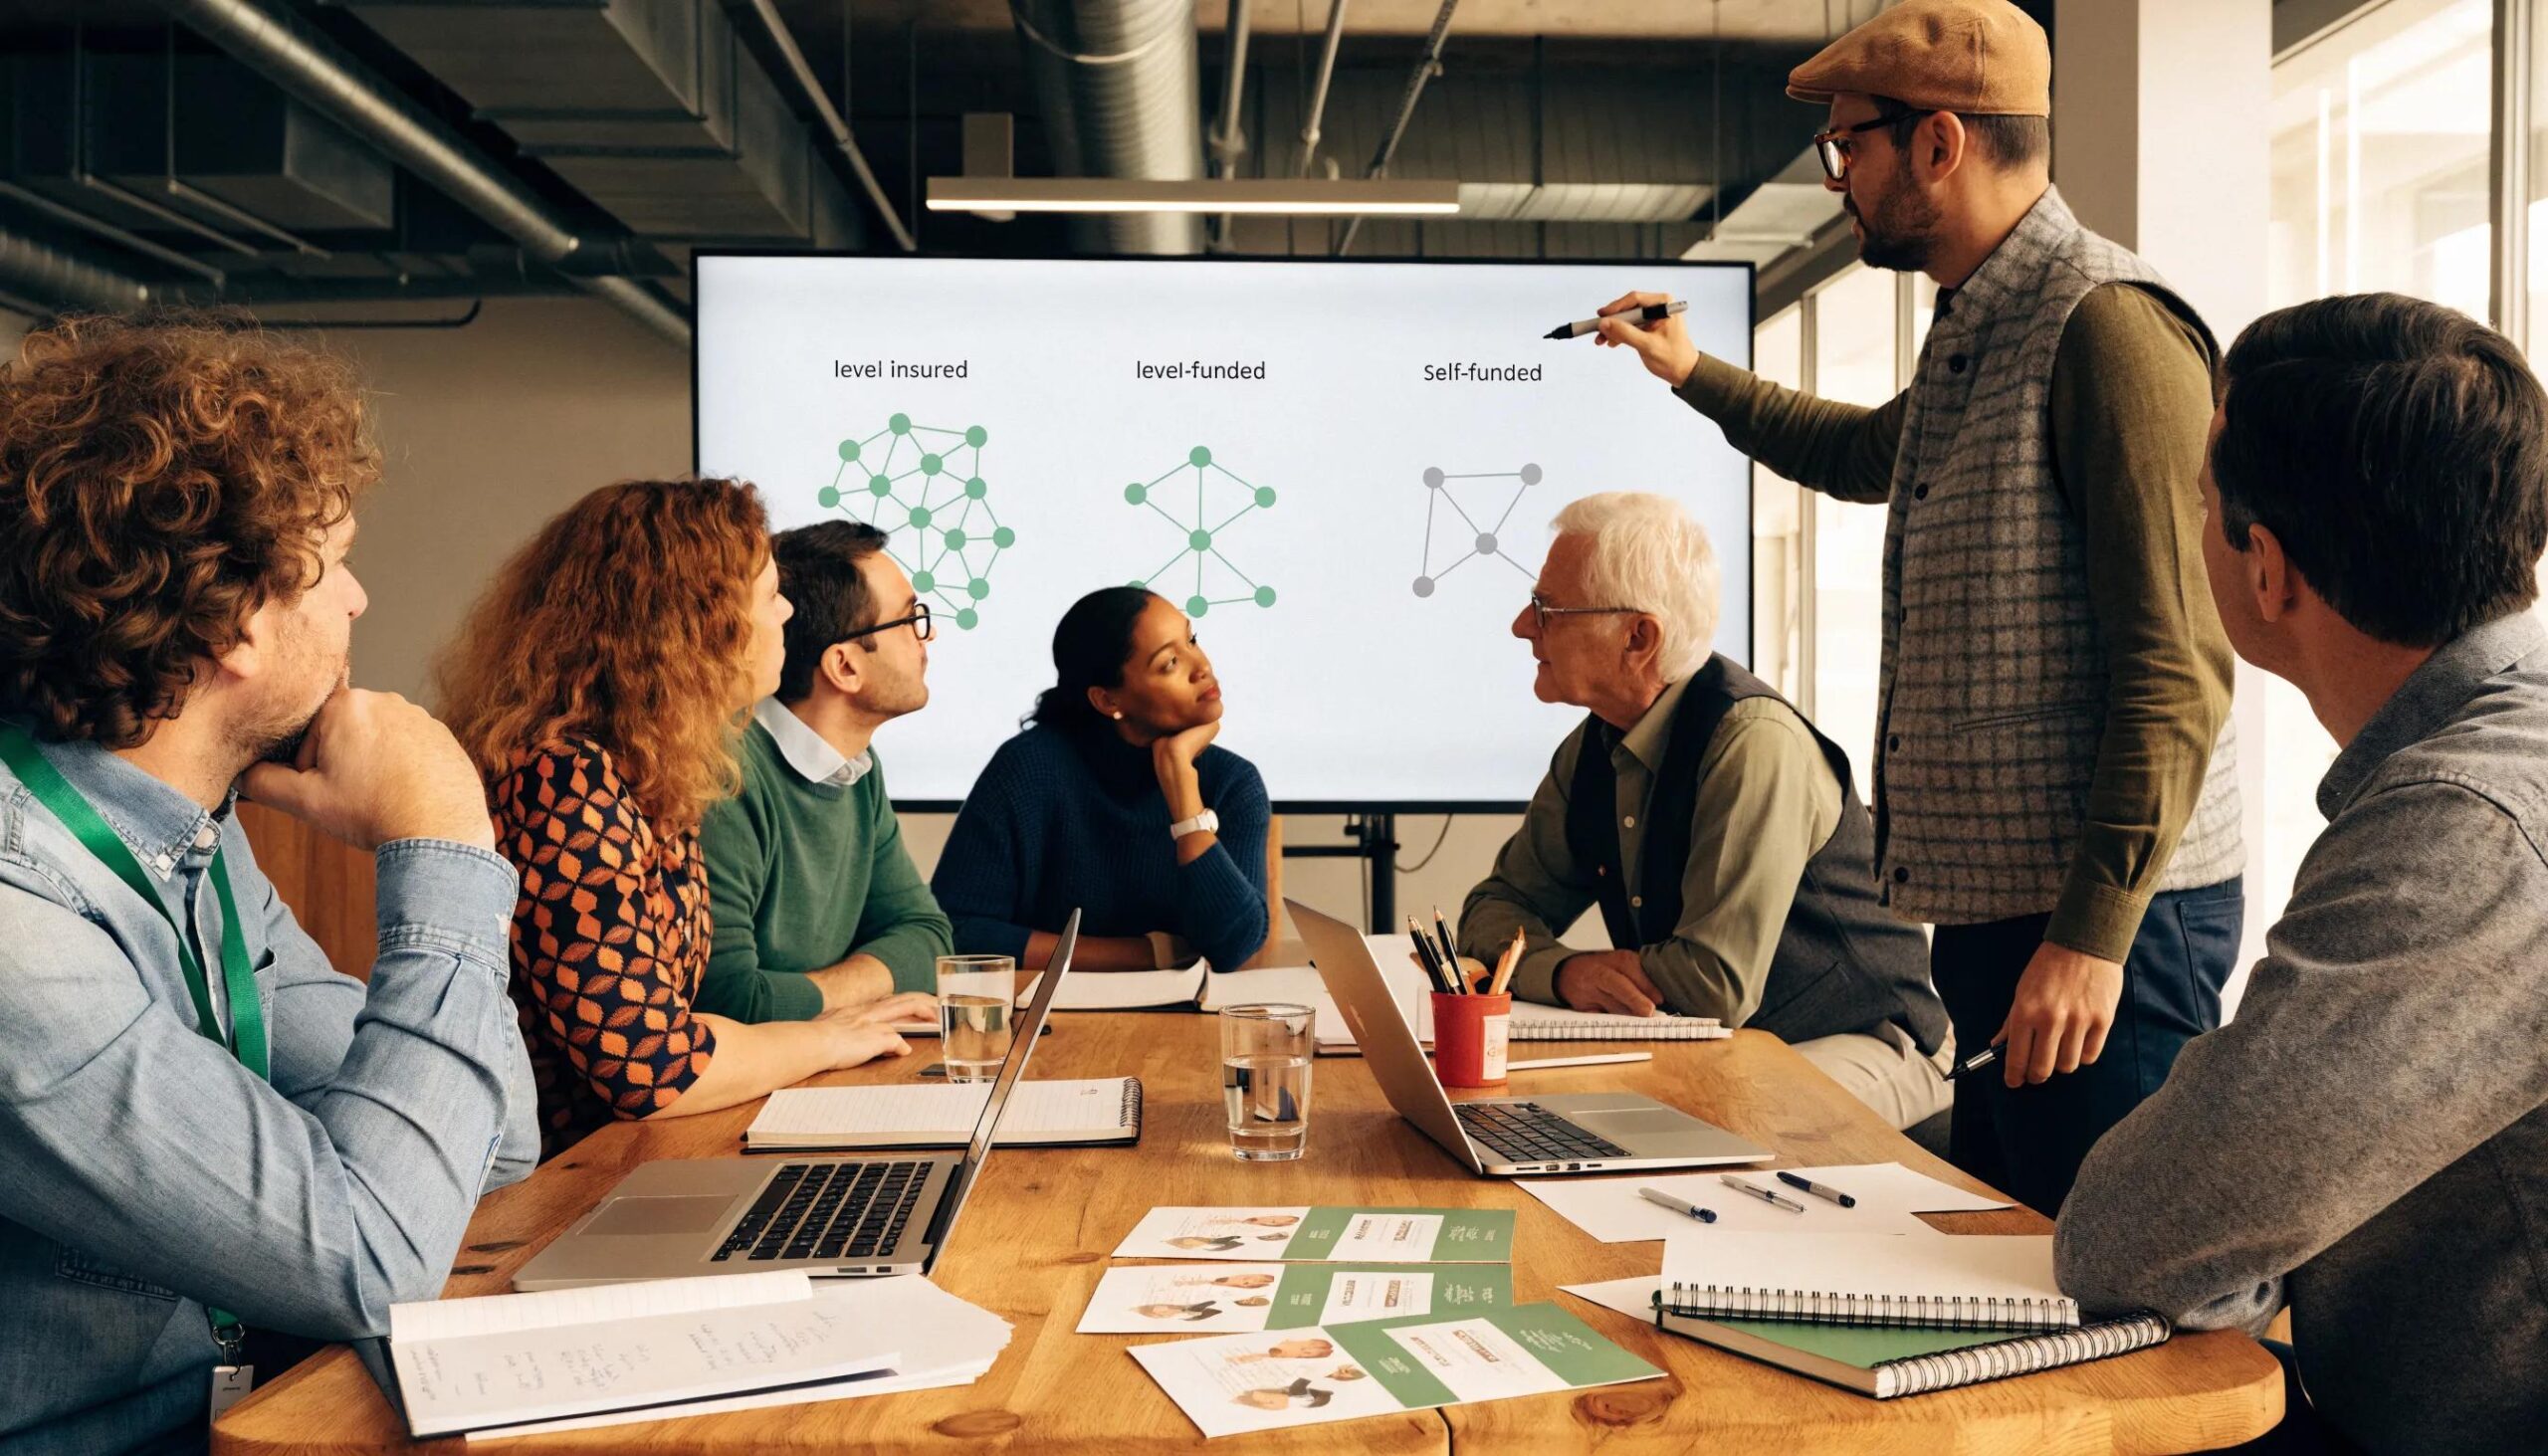
When evaluating employer health benefits South Florida, it’s essential to compare the funding models that small businesses can utilize. Below are the primary distinctions between fully insured, level-funded, and self-funded group plans:
- Fully Insured Plans: Employers pay a fixed monthly premium to an insurance provider who assumes the entire financial risk for providing healthcare services. While these plans offer more predictable costs, they can lead to higher premium increases over time.
- Level-Funded Plans: These plans combine elements of fully insured and self-funded models, providing the benefits of predictable monthly costs while allowing businesses to retain unused premium dollars. Employers pay a set amount, and if claims are lower than expected, the surplus is returned.
- Self-Funded Plans: Also known as self funded group health plans Florida, these allow businesses to pay for employees’ medical claims directly, retaining more control over healthcare costs. While they provide greater flexibility, they also come with increased risks, as employers must ensure they have adequate funds to cover unexpected claims.
For a clearer understanding, the following table provides a side-by-side comparison of these funding models:
This detailed comparison illustrates that level funded health insurance Broward County plans and self funded group health plans Florida can be attractive for businesses seeking cost efficiency while managing risk effectively.
Individual Coverage HRAs and QSEHRAs: Defined Contribution Benefits for South Florida Employers
Health reimbursement arrangements Florida, such as Individual Coverage Health Reimbursement Arrangements (ICHRAs) and Qualified Small Employer Health Reimbursement Arrangements (QSEHRAs), represent innovative approaches for small businesses to provide health benefits. ICHRAs allow employers to reimburse employees for individual health insurance premiums and qualified medical expenses tax-free. This flexibility fosters a more personalized health benefit framework tailored to employee needs.
Understanding the differences between plans is crucial. The ICHRA vs QSEHRA differences primarily lie in eligibility and contribution limits. ICHRAs can be offered by employers of any size and provide greater flexibility in reimbursement amounts. QSEHRAs are limited to employers with fewer than 50 employees and have lower annual contribution caps but don’t require the employer to offer a group health plan.
Both ICHRAs and QSEHRAs streamline the healthcare benefits process and allow employees to choose their preferred plans, enhancing overall satisfaction while aligning with budgetary constraints.
Provider Network Optimization: Ensuring Access to Memorial Healthcare System, Baptist Health, and Cleveland Clinic Weston
A crucial consideration for group health insurance plans South Florida involves optimizing provider network access. Small businesses in Miramar and South Florida should ensure their plans offer expansive networks that include reputable healthcare providers such as the Memorial Healthcare System (including Memorial Hospital Miramar, Memorial Hospital West, and Memorial Regional), Baptist Health South Florida, and Cleveland Clinic Florida (Weston).
Employers in Miramar Park of Commerce, Weston Corporate Center, and Pembroke Pines secure in-network access by partnering with insurance carriers that have negotiated contracts with these major health systems. Business health insurance brokers Broward County specialists often assist employers in selecting plans that maximize access to these facilities, ensuring employees can receive comprehensive care without additional out-of-network costs.
Access to quality providers not only impacts employee health outcomes but is also a critical factor in employee satisfaction and retention. Understanding the nuances of provider contracts, service offerings, and geographic coverage can help employers make informed decisions about which health plans best meet the needs of their workforce. Employers should prioritize health plans that facilitate easy access to these essential healthcare services.
Ancillary Group Benefits: Dental, Vision, Group Life, and Disability Coverage
In addition to standard health insurance, offering ancillary group benefits significantly enhances the attractiveness of an employer’s benefits package. Common ancillary benefits include:
- Dental Coverage: Essential for maintaining oral health, contributing to overall health.
- Vision Insurance: Provides coverage for eye exams and corrective lenses, improving employees’ quality of life and productivity.
- Group Life Insurance: Offers security for employees’ families, providing peace of mind and financial protection.
- Disability Coverage: Protects employees from income loss due to illness or injury, ensuring financial security.
Incorporating these additional benefits facilitates higher employee morale and reduces turnover, ultimately creating a more stable workforce. Our company provides comprehensive ancillary group benefits, including dental, vision, and disability options, to support your employee retention strategies.
Moreover, integrating life insurance and retirement planning solutions with your group benefits strategy allows for a comprehensive package that addresses employees’ overall financial well-being.
Florida Small Business Tax Incentives: Section 45R Health Care Tax Credit & Section 125 Pre-Tax Savings
Several tax incentives based on specific provisions can ease the financial burden associated with providing health insurance for small businesses. Most notably:
- Section 45R Health Care Tax Credit: This credit helps qualifying small businesses reduce costs by providing a tax credit if they offer health insurance coverage to their employees. The credit amount is based on wages paid and the percentage of employee premiums covered, encouraging greater participation in employer-sponsored coverage.
- Section 125 Pre-Tax Payroll Deductions: Also known as a Cafeteria Plan, Section 125 allows employees to pay their health insurance premiums and other qualifying expenses using pre-tax dollars. This reduces taxable income for both employees and employers, enhancing overall tax efficiency while increasing take-home pay for workers.
Leveraging these incentives can result in substantial savings, enabling small businesses to invest in their workforce while maintaining sustainable operational budgets.
Step-by-Step Guide for South Florida Employers to Implement Cost-Effective Group Health Coverage
Implementing cost-effective group health coverage involves several strategic steps for South Florida employers:
- Assess Business Needs: Evaluate employee demographics and healthcare requirements to determine the most beneficial plan structures.
- Engage in Market Research: Investigate various insurance options and funding models, including level funded health insurance Broward County plans, to identify affordable solutions that align with business objectives.
- Consult with Industry Experts: Work with insurance professionals and business health insurance brokers Broward County who can provide tailored recommendations based on current market conditions and regulations.
- Communicate with Employees: Ensure transparency with employees regarding available health coverage options for better employee engagement and satisfaction.
- Evaluate and Adjust Plans Regularly: Continuously review insurance plans to ensure they meet evolving employee needs and remain competitive in the market.
Employers who follow these steps will better position themselves to provide valuable health insurance solutions that support employee health and well-being.
Coordinating Group Benefits with Individual Health Insurance, Life Insurance, and Executive Retirement Planning
Coordinating various types of insurance coverage is essential to create a comprehensive benefits strategy. Small businesses in South Florida should strive to integrate group benefits such as medical and dental insurance with individual health insurance policies, life insurance, and retirement planning options.
By establishing cohesive strategies that align these different insurance offerings, businesses can provide holistic protection that enhances employee loyalty and satisfaction. This coordination not only supports employee welfare but can also lead to tax efficiencies for the organization, making the overall benefits package more appealing.
Through effective communication and planning, small business owners can ensure that every aspect of their employees’ insurance needs is met without redundancy or excessive costs.
Frequently Asked Questions about Small Business Health Insurance in Broward & Miami-Dade
Understanding the complexities of small business health insurance Miramar FL and the surrounding areas prompts numerous questions. Here are answers to some common inquiries:
- What are the eligibility requirements for small business health insurance in Florida? Small businesses must have between 2 to 50 employees to qualify for small group plans. Employers should contribute at least 50% towards employee premiums to meet most carrier requirements.
- How do I choose between fully insured, level-funded, and self-funded health plans? Consider your business size, risk tolerance, and financial resources. Fully insured plans offer premium predictability and reduced risk, while level-funded and self-funded plans provide potential cost savings and more control but require more risk management.
- What are the differences between ICHRA and QSEHRA? ICHRAs are available to employers of all sizes and offer flexible reimbursement options, while QSEHRAs are limited to small employers with fewer than 50 employees and have fixed contribution limits. Both provide tax-advantaged reimbursements for individual health insurance premiums.
- How can I ensure my employees have access to local hospitals like Memorial Healthcare System, Baptist Health, and Cleveland Clinic? Work with business health insurance brokers Broward County and insurance carriers to select group health plans with provider networks that include these key facilities, particularly in Miramar Park of Commerce, Weston Corporate Center, and Pembroke Pines.
- Can small businesses obtain tax savings when offering health insurance? Yes. Utilizing the Section 45R Small Business Health Care Tax Credit and Section 125 Pre-Tax Payroll Deductions can reduce tax liabilities for both employers and employees, making health benefits more affordable.
By addressing these core questions, employers can approach their insurance decisions with confidence, ensuring that they select the best options to meet the needs of their workforce.
Want to compare your options?
Click the button below to head to our quotes page where you can enter some basic information to have our team help with your insurance!
Start a Conversation With Us
Stay Informed
Stay Ahead
See More Articles

Find Local Medicare Plan Services in Fort Lauderdale and Miami: Comprehensive Guide
Locate the best local Medicare plan services in Fort Lauderdale and Miami. You deserve expert guidance that meets your healthcare needs. Get started today!
-
Compare Medicare Options for Families in Miramar and Beyond: Local Guide
Unlock a world of family-friendly Medicare options with our local guide. Navigate choices confidently and find the best plan that suits your family's needs.
-
Medicare Plan Comparison Services for Florida Residents: Unbiased Broker Guide
Navigate Medicare plans in Florida with ease. Our unbiased broker guide helps you understand options, ensuring you choose the right coverage for your needs.